Saturday, 17 August 2013

Idol Series - Peter Lynch


The opening statement from the video says it all:

" You shouldn't be intimidated. Everyone can do well in the stock market.
You have the skill, you have the intelligence, it doesn't required any education.
All you have to have is patience, do a little research, you got it.
Don't worry about it, don't panic. You got it. "

Attached youtube video is taken from Peter Lynch's "The Stock Shop". (you can purchase it via Amazon.com with this link: http://www.amazon.com/Stock-Shop-With-Peter-Lynch/dp/B004K7LMGK)

This 55min video provides a very good introduction on how one should approach an investment idea. The video is simple and straightforward.  

The fundamental behind it  is very similar to how I would analyze a company, as I believe it is always good to have a structural method on looking at an investment. But then again, it is a science looking at it but an art appreciating it.

Below is some of the key takeaway I gotten out from watching the video twice and I hope its useful for anyone who seek to be the next Warren Buffet or Peter Lynch!

Key Highlights

1) Be observant. Sometimes the best investment ideas is through your personal interaction and experience.

2) Give your investment time to grow. A good investment takes time to grow.

3) Remember that emotional strength is needed to withstand market volatility. The key organ here is not the brain but the stomach. You need to have the stomach for risk and ask yourself what would you do if the market goes down.

4) Invest in a company with a story. A simple story is a good investment. Sometimes too complicated one might not be the best investment because it's just too hard to understand.

5) Research with things you know. If you are an engineer, look at the devices you used and if it saves you time and money, it is probably a good stock!

6) You have to understand that markets goes down. It is the nature of the market.

7) Categorize company into 5 different categories:

a) Fast Grower - Most powerful. These companies have the right formula. It will usually take 5 to 10 years, or at times 30 years to reach its full potential. Thus there is a lot of time for you to put money into it. Wait till you see evidence.
           
b) Slow Grower - Slow growth is good if you pay a good price for it. Steady growth will result to steady dividend growth. Raising dividend is a good sign.
           
c) Cyclical - They usually make expensive big and long term item investment. Do not try to time it if you have no intimate market knowledge. Pick a good cyclical company with good cash flow and low debt.
           
d) Turnaround - It is at a very depress situation. You have to check its balance    sheet, make sure they have what it takes to tide through the next 12-24 month. Note you never buy on hope. Buying on hope is akin gambling. You can buy it when you see evidence that the timing is there.

e) Asset play - It is all about the hidden value of the asset.

8) Usually the smaller a company, the bigger the potential. Imagine, it will be easy to double your revenue from US$100 million to US$200 million than doubling it from US$10 billion to US$20 billion.

9) Usually a good company or story will involved:

- Strong growth
- Good research & development (R&D)
- Cost cutting
- New product
- Good brand name
- Good balance sheet

10) P/E is simply the number of year you take to earn back your investment assuming constant earning power. Rule of thumb, 3 to 5 years is a very good business.

11) Compared P/E with industry or historical. Remember you can't predict the future but you can learn from the past.

12) Again, you need to be confident about the story.

13) Good investment story only comes once or twice a year. Always balance your upside against downside. 

Thursday, 15 August 2013

Soilbuild Reit - Balloting Results

The announcement for Soilbuild Reit balloting is out!!

Based on the 62,500,000 Units available to the public for subscription, the public offer was approximately 5.4X subscribed. This is considerably weaker compared to OUE H-Trust which garnered 19.1X over subscription.

If the first day performance of OUE H-Trust is any indication, Soilbuild Reit with a 5.4X over subscription might not perform well.

Nevertheless, we shall see how the trading works tomorrow. Below is the allocation for Soilbuild Reit:

Source: SGX Website

The link to the SGX website if you are interested:

Tuesday, 13 August 2013

New IPO Coverage - Soilbuild Business Space Reit (Soilbuild Reit)

From Company's Prospectus

1. Business Description

Industrial Reit, with a focus in business space properties. Soilbuild Reit is a Singapore real estate investment trust with an initial portfolio of quality business space properties located in Singapore. “Business space” refers to:

(i) all properties zoned as business park (which includes business space used primarily for office, including any ancillary usage, so long as such usage is permitted under the relevant regulation) and

(ii) industrial properties (including, but not limited to, ramp-up facilities, flatted factories and light industrial properties) which are used primarily for, among others, manufacturing, engineering, logistics, warehousing, electronics, marine, oil & gas, research and development and value-added knowledge based
activities.

Initial Portfolio includes 2 business parks properties & 5 industrial properties. Soilbuild REIT’s initial portfolio of properties comprises seven business space properties – two business park properties and five industrial properties. They include Solaris, an iconic business park development in one-north, Eightrium @ Changi Business Park, Tuas Connection, and West Park BizCentral.

From Company's Prospectus

Soilbuild Group is the Sponsor for the Reit. Soilbuild Group Holdings Ltd. is the Sponsor of Soilbuild REIT and will be the largest Unitholder holding a stake of 27.0% (assuming the Over-Allotment Option is not exercised). The Sponsor is a Singapore-based integrated property group with a long track record of experience in the construction and development of business park, industrial and residential real estate in Singapore. It recently listed its construction arm on the SGX.


From Company's Prospectus

High occupancy rate, with Master Lease Structure to guarantee rental stability. Soilbuild Reit has a high level of occupancy rate at 99.7%. In addition, 4 of its 7 properties are under Master Lease which provides rental stability. Below are the details of which property’s Master Lease Structure:

From Company's Prospectus

Right of First Refusal (ROFR) to 4 properties. Below are the 4 properties in which Soilbuild Reit has the ROFR.

From Company's Prospectus

2. Use of Proceeds

From Company's Prospectus

3. Financial Highlights

Offering price of S$0.78, represents 2.5% discount to NAV of S$0.80. At offering price of S$0.78, it represents a 2.5% discount to its NAV of S$0.80. 


Projected 7.5% & 7.7% distribution yield for FY13 & FY14 respectively. Based on the prospectus projection, FY13 & FY14 distribution yield is 7.5% & 7.7% respectively.

From Company's Prospectus

Valuation looks slightly cheap. By pricing it at a slight discount to the NAV, Soilbuild Reit looks slightly cheap. Comparing against its peers, Soilbuild Reit also provides a higher dividend yield.


As usual, below is the financial statements of the Reit:

From Company's Prospectus - Balance Sheet

From Company's Prospectus - Income Statement

From Company's Prospectus - Cash Flow

4. Investment Highlights

Young and modern properties with longest weighted average leasehold term for underlying land of 50.4 years compared to other industrial S-REITs. Soilbuild Reit has a young and modern properties with weighted average age of 3.4 years (by GFA). In addition, its portfolio has one of the longest average leasehold term for underlying land of 50.4 years compared to other industrial S-REITs.

Stable revenue stream from Master Leased Properties (49.1% of FY12 revenue) & upside potential from multi-tenanted properties. As mentioned above, the Master Leased Properties provides a stable revenue stream (49.1% of FY12 revenue) and the remaining multi-tenanted properties present a upside potential if there is a positive rental reversion.

From Company's Prospectus

Slightly cheap valuation. As mentioned above, valuation for Soilbuild Reit looks slightly cheap and there is some juice left in this IPO.

5. Investment Risk

Again, the dividend play is over. As mentioned in the previous Reit IPOs, the dividend play for S-REITs seems over.

Lack of upside catalyst. Investing in Reit nowadays has become more alpha selection rather than beta allocation. Although, Soilbuild Reit has a ROFR for another 4 properties, I struggle to see big upside potential as the Sponsor is not yet established enough.

6. Technical Analysis

In term of momentum, the IPO technical looks very strong. In addition, with the stellar first day performance of its Sponsor, Soilbuild Reits, I guess the demand might be good.

However, there seems to be a lot of existing Industrials Reits out in the secondary and I think fear a situation of oversupply.

Thus I’m giving this IPO a fair rating for its technical.

7. Conclusion

In a scale of 1 to 5, I will rate it at a 3.5 rating.

I like the valuation as there is still some juice left in this pricing but I’m not overly excited like Money Max, which I rate it at an “all-in” 5 rating.

Thus I guess players can put some money to work and do a pump-&-dump if it opens higher. But I doubt that it will be a flyer performance.

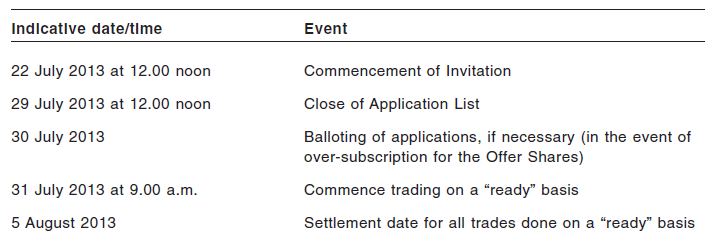
8. Timetable

From Company's Prospectus

Thursday, 1 August 2013

Money Max Financial Services Ltd (Money Max) - Balloting Results

With only 2.0 million shares on offer for the public tranche, Money Max was 638.7X over-subscribed.

Source: SGX Website

For a more detailed breakdown, please refer to the link below:

Tuesday, 30 July 2013

Rex International Holding Limited (Rex) - Balloting Results

Frankly I'm surprised by the subscription rate for Rex (153X oversubscribed!!). It seems that the momentum for Singapore IPO continues to be very strong.

Below is the final balloting results for Rex:

Source: SGX Website

For a more detailed breakdown, please refer to the link below:

Monday, 29 July 2013

New IPO Coverage - Money Max Financial Services Ltd

From Company's Prospectus

1. Business Description

Engaged in providing pawnbroking services and retail and trading of pre-owned jewellery and watches. Incorporated in 2008, Money Max is engaged in providing pawnbroking services and retail and trading of pre-owned jewellery and watches. It has since established a total of 27 outlets across Singapore under 2 brands, (1) Money Max - 26 Outlets & (2) Cash Online - 1 Outlet, enabling the company to offer its customers convenient access to its service.   

From Company's Prospectus

Pawnbroking Services

Collateralize lending. Pawnbroking services generally relate to the provision of non-recourse, short term loans secured by pledged articles. Its customers are typically individuals who require short term funds and are able to pledge valuable articles, such as jewellery and branded watches as collateral.

Retail and trading pre-owned jewellery & watches

Trading business for jewellery & watches. Max Money retails and trades pre-owned jewellery and watches which they purchase from (i) walk-in customers; (ii) independent dealers and/or traders of 2nd hand goods; (iii) from their pawnshops' unredeemed pledges which are not bid for at the licensed public auctions; and (iv) pawnshops' unredeemed pledges which they successfully bid for at the licensed public auctions


From Company's Prospectus

Despite contributing 23.2% of FY12 revenue, pawnbroking accounts for 80.8% of Profit before tax. If you look closely into the numbers, you will notice that despite contributing 23.3% of FY12 revenue, pawnbroking actually accounts for 80.8% of Profit before tax!

This is not surprising. Pawnbroking is a form of collateralize lending. As long as the customer doesn't redeem the pledged items but continue to service its interest, it can be a good source of recurrent income. Even in the event that the customer stops paying, Money Max is well protected due to the collateral it takes.   

Do note that the amount of interest that Money Max can charge is regulated under the Pawnbrokers Act whereby they are allowed to charge interest at a rate of up to 1.5% per month on the amount of the loan.

You will also notice (from the table below) that the trading business for jewellery & watches is a low margin business. This is a common trait for any physical trading as the goods they trade are pretty commoditized and one can only compete from a pricing perspective.  


Note: For a more detailed explanation of how the 2 businesses work, one can refer to page 68-71 of the Prospectus. 

2. Use of Proceeds

From Company's Prospectus

3. Financial Highlights

In the world of finance, everything is relative.

I have provided below some comparison between Money Max and its closer competitor, Maxi Cash.

Round 1: Size (Winner: Maxi Cash)


Maxi Cash currently has 2 more branches than Money Max, providing them with more distribution network. Maxi Cash also has a bigger balance sheet compared to Money Max and thus has a size advantage compared to Money Max.

Round 2: Financial Numbers (Winner: Money Max)


Despite having a smaller balance sheet and generating a smaller revenue base, Money Max actually achieved a higher Net Profit Before & After Tax compared to Maxi Cash. As a result, Money Max were able to achieve a better margin and Return on Asset. Thus, it seems to me that Money Max has a higher operating efficiency compared to Maxi Cash. 

Round 3: Valuation (Winner – Money Max)


In terms of valuation, it seems that Money Max is priced more attractively compared to Maxi Cash both on a (1) Premium over NAV and (2) PE perspective. 

4. Investment Highlights

Well-established market player. With 27 outlets strategically located across Singapore, Money Max is a well-established market player.

Low interest rate environment. Depending on your interest rate view, this can act as a double-edged sword. If the interest rate environment continues to stay low, the pawnbroking business will be a sweet spot, as Money Max can borrow low & lend higher. This will result to a very decent margin for them.

Money Max looks cheap compared to Maxi Cash. As highlighted above, Money Max looks cheap compared to Maxi Cash and on a relative value perspective, it seems like a safer bet to buy Money Max compared to Maxi Cash.

5. Investment Risk

Raising interest rate environment. Note that the amount of interest Money Max can charged is been artificially capped by the Pawnbroker Act. In the event their borrowing cost becomes higher, their margin will be squeezed.

Declining margin on its trading business. Like I mentioned above, physical trading business is a tough market as the product they trade are pretty commoditized. If you noticed its NPBT margin for its trading business, it seems to be on a declining trend, signalling how tough the business actually is.

Volatile gold price. If you have been following gold price, you should know how volatile the market has become. Being a gold trader and taking gold as pledged asset, Money Max might be exposed to the volatile price action and might get caught on the wrong side anytime.

6. Technical Analysis

Technical bid should be strong for this given the subscription history of Maxi Cash and its initial price performance.

7. Conclusion

I have a feeling that this is another “All In” IPO given the cheap valuation and strong technical bid for it.

I will definitely put money to work here.

8. Timetable

From Company's Prospectus

Saturday, 27 July 2013

New IPO Coverage - Rex International Holding Limited (Rex)

From Company's Prospectus

1. Business Operation

Independent oil and gas exploration and production (E&P) company with a set of proprietary exploration technologies (“Rex Technologies”). Scheduled to be listed on the Catalist, Rex is a small cap independent oil and gas E&P company with a set of proprietary exploration technologies - Rex Technologies. This is the 2nd E&P company listed on the SGX after the recent stellar performance of Mainboard's KrisEnergy.

Rex Technologies

From Company's Prospectus

Developed by the founders. Rex Technologies were developed by the founders of Rex Partners Ltd, Dr Karl Ligren and Mr Hans Lidgen, It comprises 3 key proprietary and innovative exploration technologies: Rex Gravity, Rex Seepage and Rex Virtual Drilling.

From Company's Prospectus

REX claims its high success ratio compared to the peers. According to the prospectus, Rex Technologies were 100% accurate in its predictions based on the 18 external tests conducted over the last 24 months. The worldwide success ratios in exploration drilling using Rex Technologies is estimated to be in excess of 50%, and Rex's Directors are of the opinion that this is much higher than the estimated average world wide and industry-wide success ratio of 10% to 15%. NOTE: Theoretically, this sound wonderful and exciting. However, I have my doubt see 5. Investment Risk.

New Start up firm with first production expected in 4Q13. Rex is a relatively young start up, incorporated only in 11 Jan 2013. Rex recently commenced a 80-well onshore drilling in the United States (7May13) and plans to drill two offshore wells in its Oman concession in late 2013 as well as the first well in each of its other two offshore concessions in the Middle East in 2014.

From Company's Prospectus

Geographically diversified concessions at more stable regulatory regimes than KrisEnergy. Rex has a diversified geographic concession  in Middle East, Norway and USA. Comparing this with KrisEnergy, these areas are considered more stable regulatory regimes. 

From Company's Prospectus

The table below provides a detailed breakdown on its concession:

From Company's Prospectus

2. Use of Proceeds

From Company's Prospectus

Note: Most of the proceed (S$36m) will be funded to its drilling expenses. It basically means that you are betting on the company's ability to achieve high success rate in its drilling. 

3. Financial Highlights

Offering price of S$0.50 represents 229.2% premium above the Net Tangible Asset (NTA). At an offering price of S$0.50, investor are paying 229.2% premium above its NTA. Thus the huge premium is equivalent to the growth potential you are paying for the company.

From Company's Prospectus

Offering price is 20% higher to pre-IPO investor. From table below, the offering price is 20% higher to the pre-IPO investors. I think this is fair given that they are taking more risk.  

From Company's Prospectus

Don't expect dividend anytime soon. Do note that Rex is a new start up and investor should not expect any dividend within the foreseeable future unless their production start stabilizing.

Financial Statements is similar to a new start-up company. Nothing unusual on its financial statement. Pretty common for a new start-up company.

From Company's Prospectus - Income Statement

From Company's Prospectus - Balance Sheet

From Company's Prospectus - Cash Flow

4. Investment Highlights

Pure growth play. Like I mention above, Rex is a pure growth play. Unlike KrisEnergy which already has existing producing fields, Rex only starts its first concession in May 2013. Thus basically you are betting on the company ability to deliver on all its promises. This is really a case of high risk, higher reward.

Geographic diversified concession with stable regulatory regime. This is definitely one of the highlight investing in this company. It has a geographic diversified portfolio and they are all in stable regulatory regime. Thus you can be sure that the company is not dealing with some dodgy 3rd world countries (the likes of some Africa and Latam countries) whereby you are exposed to high political risk.   

Ability to enter into partnership  deals. Rex prides that they are able to get into strong partnerships with strategic partners. Well, to a certain extent, this is definitely a strength, given that being a new company, more established guys are willing to believe in them to form a partnership deals. Nevertheless, I don't think it is anything to shout about as they are not the major oil & gas players (e.g. Exxon, Shell & etc).

From Company's Prospectus

5. Investment Risk

Rex Technologies might be over-hyped. So according to the Prospectus, it mentioned that Rex Technologies has a higher-than-average success ratio and it delivered 100% accurate predictions based on 18 external tests conducted over the last 24 months. Well unless you believe that 18 is a big sample size, this type of so-called tests is always subjected to statistical basis. So, unless they are able to give me a HUGE sample size, I would not buy the number easily.

Why do an IPO if their technology is so good and accurate? Again, this baffle me. If Rex is such a good growth story, why IPO the company to raise equity. Recall your Finance 101, equity is ALWAYS an expensive cost of capital. If the success ratio is so high, they could easily project its cash flow and go to the bank to borrow debt. Debt is cheaper and it will provide them with leverage too. By doing so and getting the production online and stabilize, I believe they can get an even higher IPO valuation!!

If I can think of that, why can't they. It makes me wonder if it is because the banks don't buy their story that's why they come out to issue equity.

Note: I need to disclaim a bit on this argument. It might sound a bit too extreme, but at guaranteedrisk.blogspot.sg, I will do this. I think it is my duty to point out all the risk factors. As per Murphy's law, anything that can go wrong will go wrong.

Management lacks the track record compared to KrisEnergy. With all due respect, I think the management are all great and capable guys. It's not easy to IPO a company, I'm not even sure if I can even do that. But unlike the KrisEnergy guys, the Rex's management lacks the track record. You should know I'm a firm believer of good management. Thus, I will need to monitor and access them myself as the time goes on to conclude on this. 

6. Technical Analysis

On the back of the stellar performance of KrisEnergy, I would say the bid for oil & gas E&P guys might be good.

Nevertheless, the stabilizing manager this time round is not CLSA but UOB Kay Hian. Thus I think the technical bid for this company will only at most be fair.

7. Conclusion

The recent IPO action has been doing pretty well and flippers should be in the money. (with the exception of OUE H-Trust which I was never a big fan for flipping it, see my article below)

Thus, investors will ask if they should do a flip on Rex?

Personally, I will be staying away from it this time round. My strategy is take a break and see how bullish & strong the IPO market really is.

Nevertheless on a fundamental perspective, Rex represents a high risk and higher return stock. If you believe the company can deliver on their production level, go in and GRAB it. If not, it is safer to stay away from such a risky investment.

Personally, at offer price of S$0.50, I will not be overly excited. However, if it eventually drop to around the pre-IPO investors' level of S$0.40, I might then go in to add some. I'm targeting the S$0.40 level, as I believe this is the "correct level" where the smart money (the pre-IPO guys) values the company. Thus, just follow the smart money =)

8. Timetable

From Company's Prospectus